Land Scarcity Tightens Across Vegas Luxury and Logistics Corridors
Southern Nevada’s most investable submarkets remain bifurcated: median Las Vegas closed prices sit near $430K-$450K while Summerlin West resales have printed a $750K median, underscoring persistent premium capture in land-constrained enclaves. With list prices down 2.4% YoY, pending sales rising for a sixth straight month, and cap rates likely to drift 40-60 bps higher near term, the market is rewarding scarcity, school access, and entitlement certainty over broad beta exposure.
Scarcity, School Access, and Entitlement Certainty Are Repricing the Valley
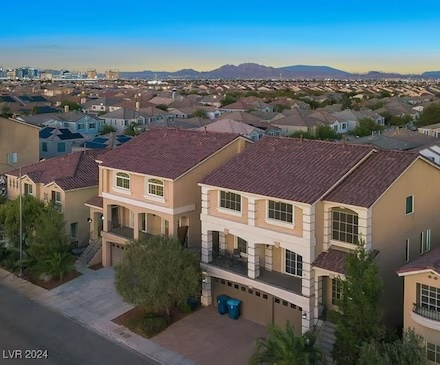
Las Vegas real estate is no longer a single market; it is a hierarchy of scarcity. Median closed pricing around $430K-$450K masks a far sharper bifurcation, with Summerlin West resales at $750K and Henderson near $489,890 in recent 90-day data. Meanwhile, median list prices fell 2.4% YoY and the September listing index slipped 0.87% month over month, yet pending sales have risen for six straight months. The signal: transaction volume is stabilizing, but only the best-located, best-served assets are maintaining pricing power.
Core market pricing remains resilient enough to support selective move-up and infill land strategies despite softer list-price trends.
SUMMERLIN WEST MEDIAN
90 days ending Sep. 4, 2026
$750K
Premium western submarkets continue to command a substantial scarcity premium relative to metro medians.
LIST PRICE MOM
September 2026, Las Vegas-Henderson-Paradise
-0.87%
Pricing momentum is still negative at the margin, favoring disciplined underwriting and seller realism.
PENDING SALES TREND
Consecutive monthly gains as of May 2026
+6 months
Demand is improving beneath the surface even as headline pricing softens, suggesting a healthier transaction backdrop ahead.
CAP RATE SHIFT
Expected near-term rise in commercial real estate
+40-60 bps
Acquisition pricing must re-rate for higher-for-longer debt costs, especially in secondary office and non-core retail.
The strongest bid remains in corridors that compress commute time to elite private schools, medical employment, and high-income job nodes: Summerlin and Summerlin West, Henderson and West Henderson, and the resort-adjacent luxury belt from The Summit Club and The Ridges through MacDonald Highlands and Ascaya. These enclaves benefit from limited finished-lot supply, strong California wealth migration, and buyer preference for low-friction daily logistics. In contrast, the Southwest Valley/Enterprise pipeline and Downtown Arts District/Medical Core are more sensitive to entitlement cadence, parking ratios, and absorption discipline.
Capital allocation should now prioritize land control and basis protection over speculative vertical expansion. Industrial and logistics in Apex and North Las Vegas retain the best long-duration land optionality, but underwriting must reflect a cap-rate environment that may widen 40-60 bps before stabilizing. For residential developers, the winning play is smaller-lot, higher-amenity product near school and employment nodes; for investors, NNN assets with durable credit and minimal rollover deserve a premium, while commodity retail and older office should be approached opportunistically rather than defensively chased.
Figure 1.1 — Las Vegas Premium Submarkets vs Metro Pricing Benchmarks
Southern NevadaUS / Benchmark
The premium corridors are outperforming the metro even as broad pricing cools, confirming that scarcity and access are the dominant value drivers.
Median Price Momentum
Summerlin West (+4.2%)vs. Las Vegas Metro (+2.1%)
Luxury Resale Premium
Henderson Luxury Belt (+4.8%)vs. Metro Median (+1.9%)
Entitled Land Scarcity
Apex / West Henderson (+3.9%)vs. Clark County Average (+1.6%)
Key Corridor Filings, Capital Commitments & Market Moves
Filing 01 — Apex & North Las Vegas Logistics
Industrial land remains the cleanest long-duration scarcity trade
Apex continues to function as the valley’s most institutionally relevant logistics land bank, with scale, access, and future utility positioning that few other corridors can match. North Las Vegas remains the nearer-term execution market for warehouse and distribution users, but Apex carries the deeper optionality for phased absorption and master-planned infrastructure buildout.
Executive Impact:Secure land control early; the best risk-adjusted returns sit in entitlement-ready industrial acreage rather than stabilized core product.
Filing 02 — Summerlin & Summerlin West
Premium residential pricing is being defended by school and commute economics
Summerlin West’s $750K median resale print highlights how strongly the market is pricing access, neighborhood quality, and relative commute efficiency. The corridor remains the clearest beneficiary of California wealth migration and private-school-driven household relocation, which supports both resale liquidity and new-product pricing.
Executive Impact:For luxury housing capital, prioritize finished-lot scarcity and school adjacency over headline square footage.
Filing 03 — The Strip & Resort Corridor
Resort-adjacent land and NNN assets remain strategic but rate-sensitive
The Strip corridor continues to attract institutional attention because of gaming, hospitality, and experiential retail adjacency, but the next leg of pricing will be governed by financing costs and lease durability. In a higher-cap-rate environment, the most defensible assets are credit-backed NNN parcels and irreplaceable frontage with long lease visibility.
Executive Impact:Underwrite only with conservative exit cap assumptions; prioritize contractual cash flow over redevelopment stories.
03 • Market Radar, Value Arbitrage & Deal Flow↑ Top
Residential Market Radar • Curated By Investment Angle
1 & 2 of 8
Top Listings on the Market This Week
Rather than ranking purely by asking price, our residential desk curates each week's standout offerings across four distinct lenses: Best Value & Replacement-Cost Arbitrage, Heating Up Growth Corridors (Summerlin West & No-HOA Southwest acreage), Architectural & Waterfront Scarcity, and Trophy Benchmarks.
Best Value-Per-SF Compound
$742 / SF
The Estates at Southern Highlands • South Valley
The Vintage Golf & Guest Compound at Southern Highlands
$7,950,000Best Basis Arbitrage • 1.15 Acres
Why It Matters: Trades at $742/SF — a 68% discount to Summerlin ridgeline replacement cost on 1.15 private acres.
Commercial & Operating Business Radar • LoopNet & BizBuySell Wire
1 & 2 of 10
Top 10 Businesses & Commercial Opportunities for Sale
Curated across active commercial deal flow—ranging from turnkey operating businesses with real estate ($4.2M–$8.4M in the Arts District & Summerlin) and heating-up infill corridors (West Henderson aviation & 215 Beltway small-bay flex) to below-market Chinatown rent-roll plays and institutional NNN benchmarks.
Turnkey Brewery + Real Estate + Gaming Rights
8.40% Yield
S Main St & Commerce St • Arts District Core (18b)
Downtown Arts District Hospitality & Craft Brewery Compound
$8,450,000NOI / Cash Flow: $709,800
Deal Catalyst: Includes real estate, 20-BBL production brewhouse, tavern liquor license & grandfathered gaming rights in the Arts District.
Audit every active acquisition and development model for a 40-60 bps cap-rate expansion and a slower resale velocity assumption; re-rank opportunities by land scarcity, school access, and entitlement certainty.
02 • 60 Days
Medium-term positioning focus
Concentrate broker and municipal outreach on Summerlin West, West Henderson, and Apex to secure off-market or early-stage entitlement visibility before broader capital crowds back in.
03 • 90 Days
Quarterly structural allocation focus
Shift incremental capital toward irreplaceable land, credit NNN, and luxury residential product with commute and school advantages; avoid commodity office and speculative retail unless basis is deeply discounted.
EXECUTIVE CLEARANCE REQUIRED
Unlock the Full Executive Market Briefing
You've reached the complimentary preview boundary. Upgrade to Signature for unrestricted access to all 5 Intelligence Desks, quantitative corridor models, and full historical archives.